Index Fund Investing
200+ Micro-Lessons On Building Wealth The Stupidly Simple Way
Ready to build wealth without the Wall Street jargon, high fees, or stock-picking anxiety?
Index Fund Investing is your straightforward, BS-free guide to making your money work for you—the essential companion to Fiery Personal Finance, tackling the other half of the financial independence equation: what to actually do with the money you save. You don't need to be a finance genius or spend hours watching the ticker. This guide breaks down the simple, proven power of index funds, showing you how to build a resilient, hands-off portfolio that captures your fair share of market growth. Created by an engineer-turned-finance-nerd who favors math over hype, it's the roadmap to investing with total confidence—stop gambling with your future and start executing a strategy backed by the academics.
Two sisters saved the same $625/month for 40 years. One played it safe and ended up with $578K. The other invested it and ended up with nearly $6 million. This course teaches you to be the second sister.
Skip the get-rich-quick nonsense — get 200+ pieces of evidence-based investing wisdom instead.
Know exactly what separates index funds, mutual funds, and ETFs — and why passive beats active almost every time.
Walk away knowing exactly which brokerage, which accounts, and how to keep more of your returns from the IRS.
Bite-sized micro lessons built to actually finish, not another course that dies in your watch-later list.
Press play to watch the trailer.
Roadmap
1. Save vs Spend
1.1 You Can't Invest If You Spend It All
1.2 True Wealth Is an Iceberg
1.3 Your Savings Rate
1.4 The Impact of Your Savings Rate
1.5 How Much Do You Need to Retire?
1.6 FI Number
1.7 Years to Reach Financial Independence
2. Start Early
2.1 Why Time Is Your Superpower
2.2 Simple Interest vs Compound Interest
2.3 The Doubling Penny
2.4 Rule of 72
2.5 The Historical Return Before Inflation: 10%
2.6 The Historical Return Accounting for Inflation
2.7 Words of Wisdom
2.8 Mr. Early vs Mr. Late
2.9 The Power of Starting Early
2.10 The Power of Investing More
2.11 Your First $100k Is the Hardest
3. Bonds
3.1 Bonds (007)
3.2 Basic Economics
3.3 What Is a Bond?
3.4 US Treasury Bills / Notes / Bonds
3.5 Corporate Bonds
3.6 Where Can You Buy Bonds
3.7 Interest Rates & Bond Prices
4. Stocks
4.1 Owning a Piece of the Pie
4.2 What Is a Stock?
4.3 Dividend Stocks
4.4 Growth Stocks
4.5 Dividend Growth Stocks
4.6 Seek Overall Gain Instead of Chasing Dividends
4.7 Real Estate Analogy
5. Passive vs Active
5.1 Do You Wanna Waste Your Time?
5.2 Alpha
5.3 Alpha Is a Zero-Sum Game
5.4 Who Are You Really Up Against?
5.5 The Market Is Smarter Than You
5.6 The Morningstar Report
5.7 The Risk of Missing the Best Days
5.8 The SPIVA Report
5.9 The Million-Dollar Bet
5.10 Tulip Mania
6. Diversification
6.1 Why Picking Winners Is a Sucker's Bet
6.2 Example of Concentrated Portfolio
6.3 Example of Diversified Portfolio
6.4 The Math of Not Losing Everything
6.5 You Can't Predict Winners
6.6 Why You Should Stop Trying to Pick Winners
6.7 Sleep Better at Night
6.8 How Many Stocks Should You Own?
6.9 Why Last Year's Winner Is Next Year's Loser
7. Index Funds, Mutual Funds, and ETFs
7.1 Baskets of Stocks and Bonds
7.2 What Is a Mutual Fund?
7.3 What Is an Index Fund?
7.4 What Is an ETF?
7.5 Expense Ratios
7.6 Here Are the Major Indices
7.7 Two Major Stock Exchanges in the United States
7.8 What to Choose?
8. Small vs Large
8.1 Market Capitalization
8.2 Does Size Matter?
8.3 Mega Cap
8.4 Large Cap
8.5 Mid Cap
8.6 Small Cap
8.7 Micro Cap
8.8 Small Cap Stocks
8.9 Small Cap vs Large Cap Performance
9. Value vs Growth
9.1 The Tortoise vs the Hare
9.2 Growth Stocks
9.3 Value Stocks
9.4 Why Buy Value Stocks?
9.5 P/E Ratio
9.6 Growth vs Value
9.7 P/E Ratio Example
9.8 P/E Ratio Historical Reference
10. Small Cap Value
10.1 The Small + Value Combo Meal
10.2 Small Cap Value's Long-Term Track Record
10.3 The 10-Year Reality Check
10.4 The 40-Year Wealth Explosion
10.5 So… All in on Small Cap Value?
10.6 The Actually Smart Approach
10.7 There's No Magic Here
11. US vs International
11.1 Should You Invest Beyond America's Borders?
11.2 The Real Risks of International Investing
11.3 Why Invest Internationally Anyway?
11.4 Developed vs Emerging Markets
11.5 How Much International?
11.6 The Cautionary Tale of Japan
11.7 Diversify Not Just in Geography
12. Target Date Index Funds
12.1 The Investing Autopilot
12.2 How Target Date Funds Actually Work
12.3 Two Flavors
12.4 What's Actually Inside a Target Date Fund
12.5 Picking Your Target Year
12.6 The Glide Path in Detail
12.7 Why Target Date Index Funds Are Actually Great
12.8 The Downsides
12.9 The Hybrid Approach
13. Taxes on Investments
13.1 Uncle Sam Wants His Cut
13.2 Ordinary Tax Rates (Unfavorable)
13.3 Preferred Tax Rates (Favorable)
13.4 Holding Period Matters
13.5 The Tax Forms You'll Receive
13.6 Legal Ways to Keep Your Money
13.7 High Tax Bracket Strategy
13.8 Low Tax Bracket Strategy
13.9 Middle Tax Bracket Strategy
14. Risk
14.1 What Actually Keeps You Awake at Night
14.2 Understanding Your Risk vs Reward Trade-off
14.3 Standard Deviation
14.4 Beta
14.5 Sharpe Ratio
14.6 Sortino Ratio
14.7 Worst Drawdowns
14.8 Single-Day Crashes
14.9 Crash Frequency
14.10 The Mindset You Need to Stay Calm
15. Buy and Hold
15.1 The Strategy of Doing Nothing And Getting Rich
15.2 Why Buy and Hold Works
15.3 Why Market Timing Doesn't Work
15.4 "Who Knows? We Shall See"
15.5 Investing Psychology Is Not Intuitive
15.6 Presidents Come and Go—Markets Grow
15.7 Why Humans Lose
15.8 Stock Market Rebounds All the Time
15.9 Look at the Big Picture
15.10 Holding Period vs Returns
15.11 The Doomsday Prophets Are Often Wrong
15.12 Bull Markets, Bear Markets, and Corrections
15.13 The Best Days Happen During the Worst Times
15.14 The Devastating Cost of Missing the Best Days
15.15 Time in the Market Beats Timing the Market
16. Dollar-Cost Averaging vs Lump Sum
16.1 The $50,000 Question
16.2 What Is Dollar-Cost Averaging?
16.3 How Dollar Cost Averaging Actually Works
16.4 The Psychology of Dollar Cost Averaging
16.5 "Buy the Dip" Is Mostly Nonsense
16.6 What Is Lump-Sum Investing?
16.7 When to Use DCA vs Lump Sum Investing
16.8 What the Research Actually Says
16.9 The Hybrid Approach
16.10 Make Investing Automatic
17. Brokerage Wars
17.1 Where You'll Grow Your Money
17.2 The Big Three
17.3 Vanguard
17.4 Fidelity
17.5 Charles Schwab
17.6 Ownership Structures
17.7 The Big Three Compared
17.8 How to Choose
18. Account Types
18.1 Where You Actually Put Your Money
18.2 The 401(k)
18.3 The Roth IRA
18.4 Health Savings Account
18.5 Taxable Brokerage Account
18.6 The Wealth Allocation Roadmap
19. Accounts for Children
19.1 The Airplane Oxygen Mask Rule
19.2 The 529 Plan
19.3 Custodial Roth IRA
19.4 UGMA / UTMA
19.5 My Personal Bias
20. Asset Location
20.1 Location—Not Allocation
20.2 The Three Account Types
20.3 Taxable Brokerage Account
20.4 Roth IRA (Tax-Free)
20.5 Traditional 401(k) (Tax-Deferred)
20.6 Exceptions, Caveats, and Nuances
21. Asset Allocation
21.1 The Cooking Analogy
21.2 There's No One Perfect Portfolio
21.3 The Decision Tree
21.4 One-Fund Solutions
21.5 Two-Fund Solutions
21.6 Three-Fund Solutions
21.7 Target Date Index Funds
21.8 Total US Stock Market Index Funds
21.9 S&P 500 Index Funds
21.10 Total World Stock Market
21.11 US Small Cap Value
21.12 Total International Ex US Stock Market
21.13 The Play Money Rule
21.14 My Asset Allocation
21.15 Wealth Accumulation (Taxable)
21.16 Wealth Accumulation (Tax-Sheltered)
21.17 Wealth Preservation (Taxable)
21.18 Wealth Preservation (Tax-Sheltered)
21.19 Decision Soundness
22. Rebalancing
22.1 What Is Rebalancing
22.2 Buy and Sell Method (The Tax-Sheltered Strategy)
22.3 Cash Flow Rebalancing (The Taxable Strategy)
22.4 Automatic Rebalancing
22.5 Dynamic Rebalancing
22.6 Rebalancing Prioritization
22.7 Rebalancing Frequency
22.8 The Problem with Automatic Investments
22.9 Rebalancing Strategies
22.10 The Glide Path
23. Tax Avoidance
23.1 Tax-Loss Harvesting
23.2 Tax-Loss Harvesting Rules
23.3 Tax-Loss Harvesting Example
23.4 Offsetting Gains and Income
23.5 Is Tax-Loss Harvesting Worthwhile?
23.6 Backdoor Roth IRA
23.7 Backdoor Roth Tax Considerations
23.8 Pro-Rata Rule Example
23.9 Conversion vs Recharacterization
24. Drawdown
24.1 You Hit Your FI Number. Now What?
24.2 The Safe Withdrawal Rate
24.3 How It Works
24.4 Drawdown Order
24.5 Drawdown Frequency
24.6 Roth Conversion Ladder
24.7 Roth IRA 5-Year Clocks
24.8 Section 72(t) / SEPP
24.9 Rule of 55
24.10 Pay the Penalty
24.11 Consult a Professional
25. Bonus
25.1 The Stuff That Didn't Fit Anywhere Else
25.2 Interview Your Financial Advisor
25.3 What to Do With Your Old 401(k)
25.4 Investment Policy Statement
25.5 Thou Shalt Not
25.6 Common Investing Myths
25.7 Allow Me to Ramble
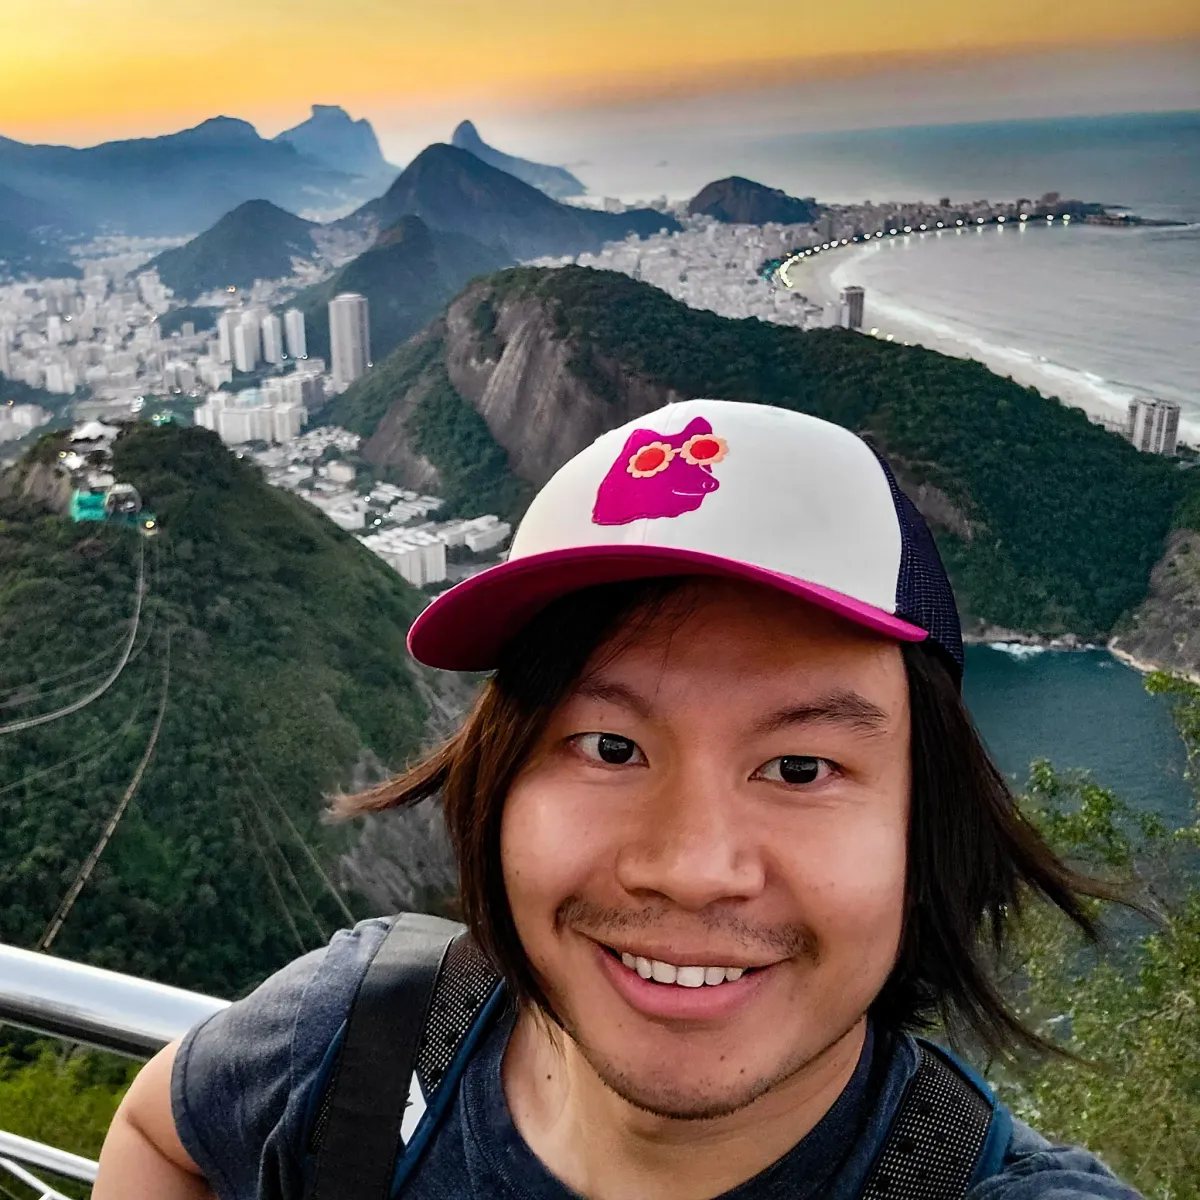
Who am I?
I'm an engineer-turned-finance-nerd who lives by the principles I teach. After immigrating to the US from the Philippines in 2002, I earned degrees in Electrical Engineering and Physics and spent 17 years in the semiconductor industry. Driven to master money, I passed the Series 65 (Uniform Investment Adviser Law Exam) and founded Fiery Personal Finance to teach a simple, BS-free framework: spend less than you earn and invest the difference. As an Eagle Scout, photography enthusiast, and adventurer, I've explored over thirty countries across six continents. When I'm not helping people fast-track their financial independence, I'm outside mountain biking, snowboarding, or hiking around the Pacific Northwest.
— Ernesto
FAQ
Why not just VTSAX and chill?
Because that's not your decision — you borrowed someone else's. When the market crashes, and it will, you won't have the same conviction holding a portfolio you didn't understand as you will holding one you built yourself, with real knowledge of why every piece is there.
Does this course cover budgeting, getting out of debt, or buying a house?
No — this is investing only. The personal-finance mechanics that fund those investments — debt, credit, budgeting — live entirely in the companion course, Fiery Personal Finance.
The market is at an all-time high right now. Shouldn't I wait for a crash?
No — time in the market beats timing it, every time the data's been checked. Miss just the 10 best days over a 40-year stretch and you can cut your returns in half. Wait for a dip, and the math says you'll likely miss the gains instead.
What happens to my money if the market crashes right after I invest?
Every crash in market history has eventually hit a new all-time high. The real risk was never the portfolio dropping — it's you panicking and selling at the bottom.
I'm in my 40s or 50s. Is it too late for me to start?
Starting late beats never starting, full stop. At 45 or 55, you've still got decades — before and during retirement — for compound interest to do the work.
Is this too technical for me?
No. Mostly beginner-to-intermediate, with a splash of advanced material for when you're ready for it. You don't need to already understand money to start — you need to be willing to learn.
What if I prefer reading or listening instead of watching videos?
Should I get the Bundle instead?
Same logic in reverse — this course is the investing half, Fiery Personal Finance is everything else. Most people end up wanting both.
My philosophy
If you don't love what you bought, I don't want your money. Contact me within 30 days for a full refund — no questions asked. My reputation matters more to me than keeping money you felt I didn't earn. I'm here to help you build wealth, not sell you trash.
Early-adopter pricing
Fiery Personal Finance Course
200+ Micro-Lessons On Not Being Stupid With Your Money
15 chapters
7 hours of content
64 animation videos
Lifetime access on-demand
Quizzes, worksheets & calculators
Fiery Personal Finance community
Course Bundle
(Both courses)
400+ Micro-Lessons On Mastering Money & Building Wealth
40 chapters
14 hours of content
128 animation videos
Lifetime access on-demand
Quizzes, worksheets & calculators
Fiery Personal Finance community
Index Fund Investing Course
200+ Micro-Lessons On Building Wealth The Stupidly Simple Way
25 chapters
7 hours of content
64 animation videos
Lifetime access on-demand
Quizzes, worksheets & calculators
Fiery Personal Finance community


© 2026 Fiery Personal Finance LLC. All Rights Reserved.